
New housing research finds continued declines in national luxury price thresholds despite stronger conditions in selected markets.
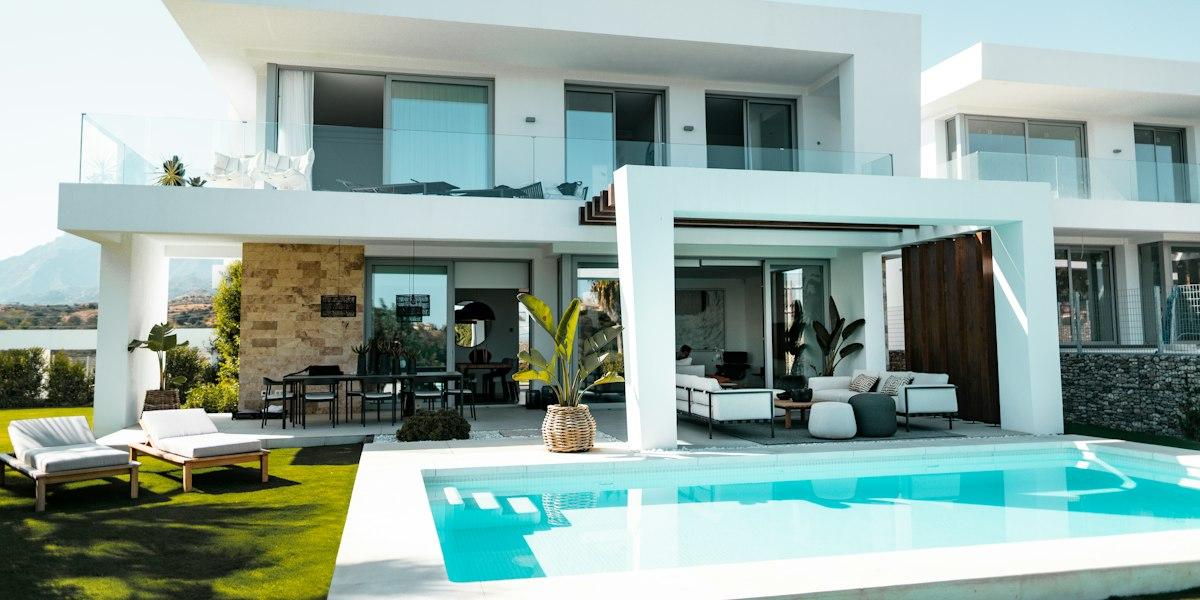
The American luxury housing market continued to experience downward price adjustments in October, with new research showing that the entry-level luxury threshold declined for the 31st consecutive month compared with the previous year. The findings highlight a changing high-end residential market in which national price indicators are weakening while selected metropolitan areas continue recording gains.
The October 2026 Luxury Housing Report released by Realtor.com Economics provides an updated view of the upper segment of the U.S. housing market. Its findings show that the national threshold for entry-level luxury listings reached approximately $1.2 million, representing a 2.3 percent annual decline.
The report also identified larger decreases among more expensive properties, suggesting that price adjustments have become more pronounced toward the highest end of the market.
Luxury Price Thresholds Continue Declining
The report defines the entry-level luxury segment through the 90th percentile of residential listing prices. In October, that threshold stood at $1,197,014.
The 95th percentile threshold, representing a higher-priced segment, reached $1,873,040, down 4.1 percent from the previous year. At the 99th percentile, the ultra-luxury threshold stood at $5,125,874, reflecting a 6.2 percent annual decline.
These figures demonstrate that the decline has not been limited to properties near the lower boundary of the luxury market.
The report found that all three price thresholds had recorded annual declines for 31 consecutive months. The larger reduction at the highest tier indicates that the most expensive listings have experienced greater price pressure than entry-level luxury properties.
The figures measure listing-price thresholds rather than completed transaction prices. They therefore provide an indication of market positioning and available inventory rather than a direct measure of the prices ultimately paid by buyers.
Regional Markets Show Different Performance
Although national luxury indicators remained negative, the research identified several metropolitan areas where high-end residential prices continued to increase.
Naples-Marco Island, Florida, recorded the strongest annual increase among the markets highlighted, with its entry-level luxury threshold rising 9 percent.
North Port-Bradenton-Sarasota, Florida, followed with a 7.7 percent increase, while Charleston-North Charleston, South Carolina, recorded growth of 4.7 percent.
Florida accounted for five of the 12 metropolitan areas that posted annual increases of at least 1 percent.
Bridgeport-Stamford-Danbury, Connecticut, ranked as the most expensive metropolitan luxury market in the report. Its entry-level luxury threshold reached $3.96 million, approximately 3.3 times the national threshold.
The regional differences demonstrate why national averages do not necessarily describe conditions in individual housing markets.
Local employment, migration patterns, property availability, construction activity and buyer preferences can influence luxury housing performance independently of national trends.
Luxury Properties Are Spending Less Time on the Market
Despite declining price thresholds, luxury listings showed improvements in marketing time.
The median luxury listing in the 90th percentile spent 73 days on the market in October, five days fewer than during the same period a year earlier.
Properties in the 95th percentile spent a median of 81 days on the market, four days faster than the previous year. Ultra-luxury listings recorded a median of 97 days, six days faster.
The overall median residential listing spent 63 days on the market, remaining essentially unchanged from the previous year.
These findings suggest that lower listing thresholds have not necessarily translated into slower marketing conditions across every luxury segment.
However, time on market alone does not establish whether sellers are receiving their original asking prices or accepting substantial negotiated reductions.
The Share of Million-Dollar Listings
Million-dollar listings represented 12.3 percent of the residential market in October, declining by half a percentage point from the previous year.
This movement provides another indication of changing conditions in the upper-priced housing segment.
The proportion of million-dollar properties can be affected by several factors, including changes in asking prices, new listing activity and the geographic distribution of available homes.
A declining share does not necessarily mean that demand for luxury housing has disappeared. Instead, it reflects the relationship between the number of properties priced at or above the threshold and the broader listing inventory.
Implications for the Real Estate Industry
The latest findings offer important context for brokers, residential developers, property analysts and real estate professionals working in the luxury segment.
The continued decline in national price thresholds suggests that sellers may need to evaluate pricing strategies more carefully, particularly in markets where expensive properties are experiencing larger adjustments.
For buyers, the figures provide evidence that some high-end listings are being repositioned as market conditions change. Nevertheless, affordability and purchasing decisions remain influenced by mortgage costs, available financing and local property values.
The regional gains also emphasize the importance of examining individual metropolitan markets rather than relying exclusively on national housing indicators.
The October report illustrates a luxury housing market undergoing gradual adjustment rather than moving uniformly in one direction. Declining national thresholds, improving marketing times and stronger performance in selected metropolitan areas collectively demonstrate the complexity of the American high-end residential market.

Top Listings Contributor
Covers market analysis and property technology, tracking where the data and the tools are pushing the industry next.
This article features partner, contributor, or branded content from a third party. Members of the Top Listings editorial staff were not involved in the creation of this content. All views and opinions are those of the contributor alone.
Related Posts