
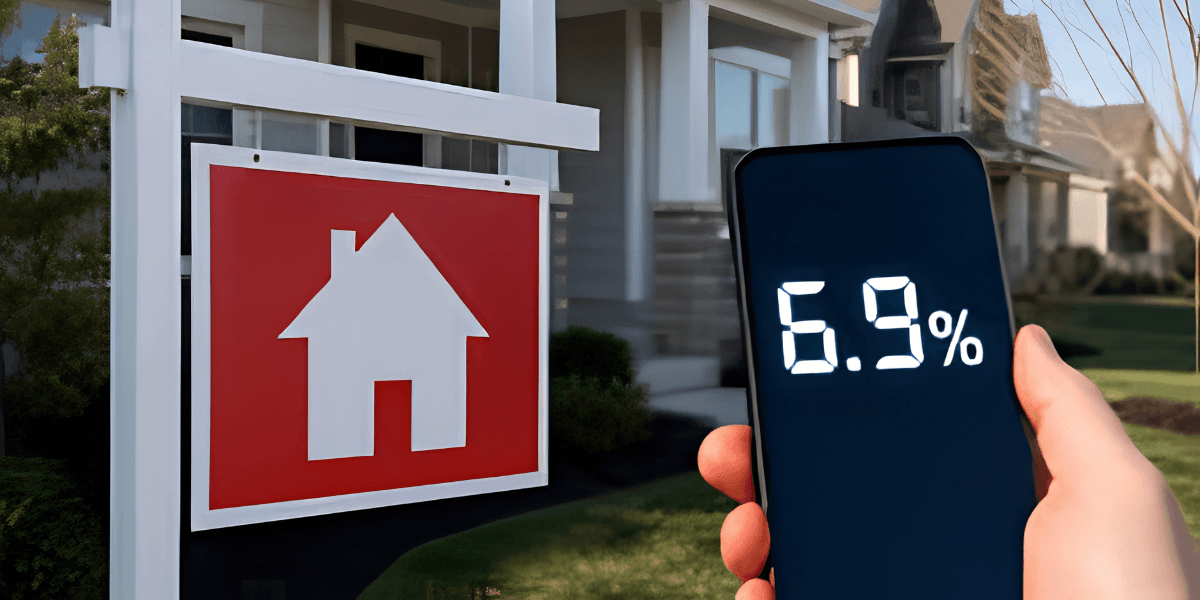
High mortgage rates, elevated home prices and limited supply continue to constrain the U.S. housing market.
Housing Market Enters Another High-Rate Period
The U.S. housing market is continuing to operate under elevated borrowing costs, with mortgage rates remaining close to 7 percent and creating challenges for buyers, sellers and builders.
The financing environment follows a period of rising long-term Treasury yields and changing expectations about inflation and monetary policy.
Mortgage rates are especially important to residential real estate because most home purchases depend on financing.
When rates rise, the same home requires a larger monthly payment than it would under a lower-rate environment.
That relationship has become one of the central factors shaping the housing market.
Buyers Face Reduced Purchasing Power
Higher mortgage rates can reduce the amount of money a household can borrow while maintaining an affordable monthly payment.
A prospective buyer who qualified for one price range when rates were lower may qualify for a smaller loan when rates rise.
That can lead buyers to search for less expensive properties or delay purchases.
The effect is particularly significant because home prices remain elevated in many parts of the country.
The combination of high property prices and expensive financing means buyers face pressure from two directions.
Affordability also varies substantially by location. Housing markets with lower prices can remain more accessible than expensive metropolitan areas, even when mortgage rates are identical.
Existing Homeowners Affect Supply
The current rate environment also affects homeowners who might otherwise consider selling.
Many existing homeowners secured mortgages when interest rates were substantially lower.
Selling a property and purchasing another can require replacing that older financing with a new mortgage carrying a considerably higher rate.
That creates a financial incentive for some homeowners to remain in their current properties.
The resulting effect can contribute to limited inventory in some markets.
Low inventory can support home prices because buyers have fewer properties from which to choose.
However, affordability constraints can simultaneously reduce the number of households capable of completing a purchase.
Builders Face a Difficult Environment
Homebuilders are also dealing with the effects of elevated financing costs.
Construction companies require capital to acquire land, finance development and build properties.
Higher borrowing costs can raise the cost of development.
Builders must also consider whether potential buyers can afford newly constructed homes.
Recent industry data showed builder confidence at a one-year low, reflecting concerns over mortgage rates, labor availability and material costs.
Some builders have responded with price reductions and sales incentives to attract buyers.
That approach can help individual developments move inventory, but it also illustrates the broader affordability pressure affecting the market.
New Construction Remains Important
Despite the difficult environment, new construction remains an important source of housing supply.
Recent government data showed that single-family housing starts increased during the summer, although permits for future construction declined.
That combination creates uncertainty about the pace of construction ahead.
Housing starts measure projects already beginning construction, while building permits provide an indication of future development activity.
A decline in permits can therefore signal weaker construction activity later if developers postpone projects.
The relationship between financing, demand and construction remains central to the housing outlook.
Regional Differences Remain
The national housing market is not a single uniform market.
Local employment, population growth, construction costs, land availability and housing inventory can produce very different conditions.
Some metropolitan areas continue to experience strong demand, while others have seen slower sales.
The effect of mortgage rates also varies depending on local prices.
A small change in rates can have a much larger impact on monthly payments for an expensive property than for a lower-priced home.
Real Estate Professionals Adjust
Real estate agents, lenders and builders are adapting to the continued high-rate environment.
Agents must work with buyers whose budgets are constrained by financing costs.
Lenders are operating in a market where refinancing activity is limited because many homeowners already hold lower-rate mortgages.
Builders are balancing construction costs with the purchasing power of potential customers.
The result is a market in which financing conditions influence nearly every part of the residential transaction.
A Market Defined by Affordability
The housing market's current challenge is not simply the level of mortgage rates.
It is the combination of borrowing costs, home prices, inventory and household incomes.
Even if rates eventually decline, affordability could remain difficult if home prices continue to exceed what many households can comfortably finance.
For the moment, the near-7-percent mortgage environment remains an important force shaping decisions across the housing industry.
Buyers, sellers, builders and real estate professionals are all operating in a market where financing conditions continue to influence demand and supply.

Top Listings Contributor
Covers market analysis and property technology, tracking where the data and the tools are pushing the industry next.
This article features partner, contributor, or branded content from a third party. Members of the Top Listings editorial staff were not involved in the creation of this content. All views and opinions are those of the contributor alone.
Related Posts